Maximize Your 2026 HSA Benefits: 15% Tax Advantage Guide
Anúncios
Maximizing your 2026 Health Savings Account (HSA) benefits involves strategic contributions, understanding tax advantages, and leveraging investment opportunities to secure your healthcare future and financial well-being.
Anúncios
Are you ready to truly understand and strategically utilize one of the most powerful financial tools available for healthcare expenses? To maximize your 2026 Health Savings Account (HSA) benefits: a 15% tax advantage guide is essential for anyone looking to optimize their financial health. This comprehensive guide will walk you through the nuances of HSAs in 2026, ensuring you’re well-equipped to make the most of this triple-tax-advantaged account.
Anúncios
Understanding the 2026 HSA Landscape and Eligibility
The Health Savings Account continues to be a cornerstone of savvy financial planning for healthcare. In 2026, understanding the updated regulations and eligibility criteria is paramount to ensure you can fully participate and reap its substantial benefits. Eligibility hinges primarily on your enrollment in a High-Deductible Health Plan (HDHP).
An HDHP is characterized by higher deductibles than traditional insurance plans, but in return, it offers lower monthly premiums. The IRS sets specific minimum deductibles and maximum out-of-pocket limits for HDHPs each year, which are crucial for HSA eligibility. For 2026, these figures are expected to see minor adjustments, reflecting inflation and healthcare cost trends. It’s vital to confirm these exact numbers as they become available from the IRS to ensure your plan qualifies.
Key Eligibility Requirements
Beyond just having an HDHP, there are other strict criteria you must meet to be eligible for an HSA. These rules are designed to ensure HSAs are used as intended: for individuals taking on more responsibility for their initial healthcare costs.
- HDHP Enrollment: You must be covered by an HDHP on the first day of the month for which you want to contribute.
- No Other Health Coverage: Generally, you cannot be covered by any other health plan that is not an HDHP, with some exceptions like vision, dental, or specific injury insurance.
- Not Enrolled in Medicare: Once you enroll in Medicare, you are no longer eligible to contribute to an HSA.
- Not Claimed as a Dependent: You cannot be claimed as a dependent on someone else’s tax return.
Understanding these eligibility rules is the first critical step in leveraging your 2026 HSA. Without meeting these foundational requirements, you cannot contribute to an HSA, regardless of its potential tax advantages. Therefore, always verify your health plan’s status and your personal circumstances against the latest IRS guidelines to ensure continuous eligibility.
Maximizing Your 2026 HSA Contributions for Triple Tax Advantage
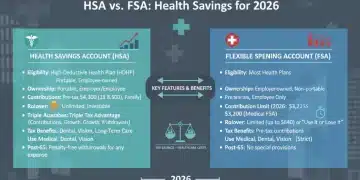
The allure of the HSA lies in its triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. For 2026, maximizing your contributions up to the annual limit is the most direct way to amplify these benefits. The IRS announces these limits annually, typically adjusting them for inflation.
For individuals, the 2026 contribution limit will likely see a slight increase from previous years. Similarly, the family contribution limit will also be adjusted upwards. Additionally, individuals aged 55 and older are eligible for a catch-up contribution, allowing them to save even more towards their healthcare future. These limits apply to all contributions made to your HSA, whether from you, your employer, or a combination of both.
Strategic Contribution Approaches
- Employer Contributions: Take full advantage of any employer contributions, as this is essentially free money that boosts your HSA balance without impacting your personal taxable income.
- Lump Sum vs. Payroll Deductions: While payroll deductions offer convenience and a consistent savings approach, consider a lump sum contribution at the beginning of the year if possible. This allows your funds to start earning returns sooner.
- Catch-Up Contributions: If you are 55 or older, make sure to utilize the additional catch-up contribution. This is a critical opportunity to build up your healthcare nest egg before retirement.
Consistently maximizing your HSA contributions in 2026 sets a strong foundation for future financial security. The earlier you contribute and the more you contribute, the greater the compounding effect of tax-free growth, leading to a substantial healthcare fund when you need it most.
Leveraging the 15% Tax Advantage: A Deeper Dive
The 15% tax advantage often cited with HSAs refers to the combined effect of federal income tax deductions, state income tax deductions (where applicable), and FICA tax savings. While the exact percentage can vary based on individual income and state tax laws, the overall benefit is substantial and multi-faceted.
When you contribute to an HSA, those contributions are typically made pre-tax through payroll deductions, meaning they bypass federal income tax and FICA taxes (Social Security and Medicare). For many, the combined federal and FICA tax savings alone can easily reach or exceed 15% of the contributed amount. If your state also offers a tax deduction for HSA contributions, the total savings can be even higher.
Understanding the Tax Savings Mechanics
Let’s break down how these tax savings work in practice. Imagine you contribute $3,000 to your HSA in 2026. If you’re in the 12% federal income tax bracket and pay 7.65% in FICA taxes, you effectively save 19.65% on that $3,000 immediately. That’s nearly $600 in instant tax savings, which is a significant return on investment before any market growth is even considered.
This immediate tax reduction makes the HSA an incredibly attractive savings vehicle, especially when compared to other retirement or savings accounts that may not offer the same FICA tax advantages. The ability to reduce your taxable income while simultaneously saving for future healthcare costs is a unique and powerful benefit that should not be overlooked.
Beyond the immediate tax deduction, the tax-free growth of your investments within the HSA means that your money compounds faster. When you eventually withdraw funds for qualified medical expenses, those withdrawals are also tax-free. This trifecta of tax benefits makes the HSA arguably the most tax-efficient savings tool available for healthcare expenses, providing a substantial financial boost over the long term.
Investing Your HSA Funds for Long-Term Growth
One of the most underutilized aspects of HSAs is their potential as an investment vehicle. Many individuals treat their HSA solely as a spending account for immediate medical expenses, missing out on significant long-term growth opportunities. For 2026, consider shifting your perspective and actively investing your HSA funds.
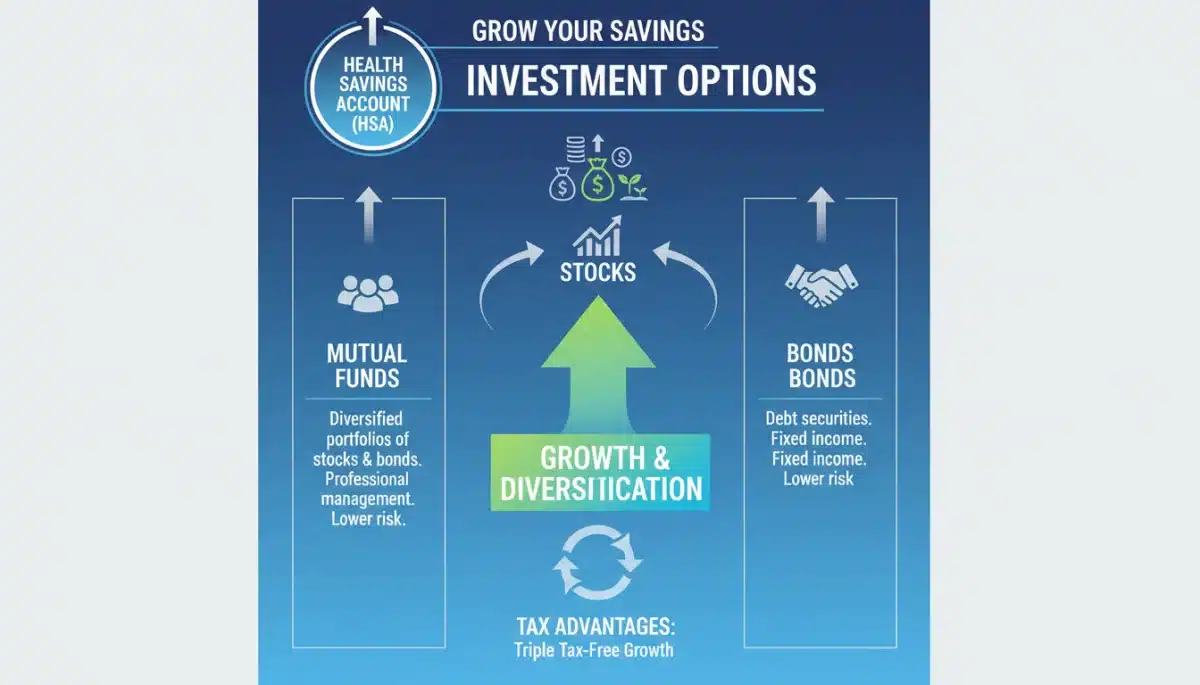
Once your HSA reaches a certain threshold (often $1,000 or $2,000, depending on the custodian), you can typically invest the excess funds in a variety of options, similar to a 401(k) or IRA. These investment choices often include mutual funds, exchange-traded funds (ETFs), stocks, and bonds. The key is to choose investments that align with your risk tolerance and time horizon, especially if you view your HSA as a supplementary retirement account.
Developing an Investment Strategy for Your HSA
Treating your HSA like a retirement account requires a thoughtful investment strategy. If you anticipate not needing the funds for many years, a growth-oriented portfolio with a higher allocation to equities might be appropriate. For those closer to retirement or with a shorter time horizon, a more conservative approach with a greater allocation to bonds might be preferred.
- Choose Your Custodian Wisely: Not all HSA custodians offer the same investment options or fee structures. Research and select a custodian that provides a wide range of investment choices and reasonable fees.
- Diversify Your Portfolio: Just like any other investment account, diversification is key. Spread your investments across different asset classes to mitigate risk.
- Rebalance Periodically: Review and rebalance your HSA investment portfolio regularly to ensure it remains aligned with your financial goals and risk tolerance.
By strategically investing your HSA funds in 2026, you can significantly enhance the account’s value. The tax-free growth over decades can turn a modest HSA into a substantial asset, providing a robust financial cushion for future healthcare costs in retirement, or even serving as a general emergency fund after age 65.
Qualified Medical Expenses: What You Can Pay For
Understanding what constitutes a qualified medical expense is crucial for maintaining the tax-free status of your HSA withdrawals. The IRS defines these expenses broadly, covering a wide range of medical, dental, and vision care. Using your HSA for non-qualified expenses before age 65 will result in both income tax and a 20% penalty, so careful record-keeping is essential.
Qualified medical expenses include payments for diagnosis, cure, mitigation, treatment, or prevention of disease, and for treatments affecting any structure or function of the body. This encompasses everything from doctor visits, prescription medications, and hospital stays to dental cleanings, orthodontia, eyeglasses, and even certain over-the-counter medications with a doctor’s prescription.
Common Qualified Expenses
- Medical Services: Doctor’s visits, specialist consultations, hospital services, surgery, physical therapy, chiropractic care.
- Prescription Drugs: Medications prescribed by a physician.
- Dental Care: Cleanings, fillings, braces, dentures.
- Vision Care: Eye exams, eyeglasses, contact lenses, laser eye surgery.
- Preventive Care: Vaccinations, health screenings, annual physicals.
It’s important to note that health insurance premiums are generally not qualified medical expenses, with a few exceptions such as long-term care insurance premiums (up to certain limits), COBRA premiums, and Medicare premiums (for those 65 and older). Always keep meticulous records of all your medical expenses and HSA withdrawals to ensure compliance with IRS regulations. This diligence will protect your tax advantages and simplify any potential audits.
HSA in Retirement: A Powerful Tool for Later Life
While HSAs are invaluable for current medical expenses, their true power often shines brightest in retirement. Many financial experts consider the HSA to be the most advantageous retirement savings vehicle, even surpassing 401(k)s and IRAs, especially for healthcare costs in later life.
In retirement, healthcare costs can be a significant financial burden. Medicare premiums, deductibles, co-pays, and services not covered by Medicare can quickly deplete savings. An HSA, with its tax-free withdrawals for qualified medical expenses, provides a dedicated and tax-efficient fund to cover these costs. After age 65, you can also withdraw HSA funds for any purpose without penalty, though these withdrawals will be subject to income tax if not used for qualified medical expenses. This flexibility makes the HSA a versatile financial tool in your golden years.
Long-Term Strategy for Retirement
To maximize your HSA’s impact in retirement, a long-term strategy is key. This involves prioritizing contributions, investing aggressively (if your risk tolerance allows), and ideally, paying for current medical expenses out-of-pocket rather than drawing from your HSA.
By allowing your HSA funds to grow untouched for decades, you accumulate a much larger sum. You can then reimburse yourself for past qualified medical expenses (as long as you kept accurate records) or use the funds for future healthcare needs in retirement. This strategy essentially turns your HSA into a super-charged investment account for health-related costs.
The ability to cover Medicare premiums, long-term care insurance premiums, and other out-of-pocket medical expenses tax-free in retirement makes the HSA an indispensable component of a comprehensive retirement plan. Don’t underestimate its potential to provide financial peace of mind as you age, making your 2026 contributions a crucial step in securing your future.
| Key Aspect | Description for 2026 |
|---|---|
| Eligibility | Must be enrolled in an HDHP and not have other disqualifying health coverage. |
| Contribution Limits | IRS-adjusted annual maximums for individuals and families, plus catch-up contributions for those 55+. |
| Tax Advantages | Triple tax benefits: deductible contributions, tax-free growth, tax-free withdrawals for qualified expenses. |
| Investment Potential | Funds can be invested for long-term growth, acting as a powerful retirement savings vehicle. |
Frequently Asked Questions About 2026 HSAs
The IRS typically announces the official HSA contribution limits for the upcoming year in the fall. While specific numbers for 2026 are not yet finalized, they are expected to increase slightly from 2025 due to inflation. Always check the latest IRS guidance for the most accurate figures.
Generally, no. To be eligible for an HSA, you must be covered by a High-Deductible Health Plan (HDHP) and have no other health coverage that is not an HDHP. Certain exceptions exist, such as specific injury insurance or dental/vision plans, but dual primary coverage usually disqualifies you.
The 15% tax advantage refers to the combined tax savings from federal income tax deductions and FICA tax exemptions on your contributions. Depending on your income bracket and state tax laws, this percentage can be even higher, making HSA contributions highly tax-efficient right from the start.
Yes, HSA funds can be invested once your account balance reaches a certain threshold, often around $1,000-$2,000, depending on the custodian. You can typically invest in mutual funds, ETFs, stocks, and bonds, similar to a traditional retirement account. Choose a custodian with diverse investment options.
HSA funds roll over year after year and never expire. If you don’t use them for medical expenses, they continue to grow tax-free. After age 65, you can withdraw funds for any purpose without penalty, though they will be subject to income tax if not used for qualified medical expenses.
Conclusion
Navigating the complexities of healthcare financing can be daunting, but the Health Savings Account stands out as an exceptionally powerful tool for both immediate and long-term financial well-being. By understanding the eligibility requirements, maximizing your contributions, and strategically investing your funds, you can truly maximize your 2026 Health Savings Account (HSA) benefits: a 15% tax advantage guide. This account offers unparalleled tax advantages, from deductible contributions to tax-free growth and withdrawals for qualified medical expenses, making it a critical component of a robust financial plan. Whether you’re planning for unexpected medical costs, saving for retirement healthcare, or simply seeking to reduce your taxable income, the HSA provides a versatile and highly efficient solution. Embrace the opportunity to take control of your healthcare finances and secure a healthier, wealthier future. Begin your digital journey with ease by leveraging these insights for your 2026 HSA strategy.